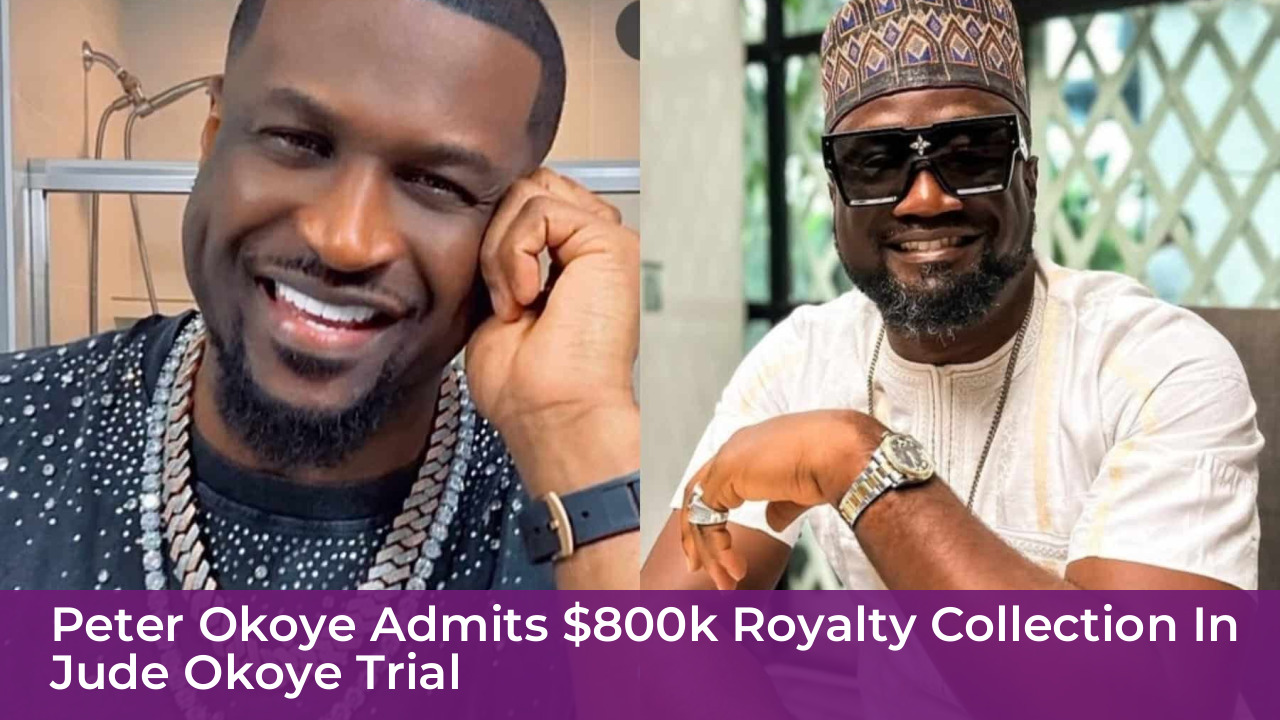
A high-profile courtroom battle within the Nigerian entertainment sector reached a critical turning point as Peter Okoye took the stand in a virtual cross-examination. Presiding over the Federal High Court in Lagos State, Justice Alexander Owoeye listened as the music artist admitted to receiving more than $800,000 in international music royalties without remitting any portion to his long-time manager and brother, Jude Okoye. The testimony forms part of an ongoing criminal trial involving multiple financial charges brought by federal anti-graft authorities.
- High Court Testimony Exposes P-Square SACEM Royalty Split
- Key Admissions Under Defense Cross-Examination
- Court Timeline and EFCC Fraud Prosecution Context
- Legal Dissection: Artist Rights vs Managerial Commissioning
- SACEM Performance Rights and Author-Publisher Rules
- The Employment Contract and Corporate Entity Debate
- The 2022 Catalog Sale Audit and EFCC Charges
- Discrepancies in Backend Royalty Records and Requests
- Evolution of Northside Music Limited Financial Operations
- Broader Legal Impact on Nigerian Entertainment Sector
- Standardizing Music Catalog Ownership and Management Contracts
- Next Steps for the Federal High Court Trial in December 2026
- Frequently Asked Questions
- What is the core dispute in the Peter Okoye and Jude Okoye court case?
- What are SACEM royalties, and why did Peter keep them?
- What are the charges brought by the EFCC?
- When does the trial resume?
The legal proceedings stem from a seven-count criminal charge filed by the Economic and Financial Crimes Commission. The prosecution accuses Jude Okoye and his corporate entity, Northside Music Limited, of diverting funds totaling N1.3 billion and $1 million. During the intense virtual court session, defense counsel Clement Onwuewunor, SAN, pressed the singer regarding global royalty collection accounts and internal financial disclosures dating back to the group’s active recording years.
High Court Testimony Exposes P-Square SACEM Royalty Split
During the virtual cross-examination before Justice Alexander Owoeye, Peter Okoye addressed the distribution of funds originating from SACEM, the French professional royalty collection society. Between 2016 and 2022, substantial performance royalties flowed from European territories into personal accounts controlled by the artist. When questioned directly about whether his manager received any share of these foreign disbursements, the witness offered a blunt response.
The core of the artist’s argument rests on the structural definition of group membership. According to the testimony, SACEM disbursements are strictly allocated to performing artists and song creators. Because Jude Okoye functioned purely in a managerial capacity rather than as a recording member of the P-Square duo, the witness maintained that no direct payment obligations existed regarding international performance rights collections.
Key Admissions Under Defense Cross-Examination
Defense counsel Clement Onwuewunor, SAN, systematically probed the financial separation between the brothers during the cross-examination. When asked why financial statements and remittances were withheld from the manager, Peter Okoye stated firmly that Jude is not part of P-Square. This declaration formed the legal justification for excluding the manager from multi-year foreign royalty disbursements.
However, questioning revealed a specific historical exception. The witness acknowledged a solitary instance prior to corporate disputes where a 25 percent share of a specific SACEM distribution was remitted to Jude Okoye. Defense lawyers utilized this admission to question the consistency of the artist’s claims regarding exclusive author-only distributions, setting the stage for deeper document examinations in upcoming hearings.
Court Timeline and EFCC Fraud Prosecution Context
The courtroom disclosures are directly tied to the seven-count criminal charge filed by the Economic and Financial Crimes Commission against Jude Okoye and Northside Music Limited. The sweeping allegations involve financial irregularities scaling up to N1.3 billion and $1 million. These figures represent accumulated earnings, master recording assets, and corporate revenues generated during decades of active touring and album releases.
As the legal teams prepared to conclude the current hearing phase, Justice Alexander Owoeye formally adjourned the trial. Courtroom proceedings are scheduled to resume on December 8 and 9, 2026. These upcoming dates will feature further cross-examinations and defense submissions designed to scrutinize backend accounting books.
Legal Dissection: Artist Rights vs Managerial Commissioning
The bitter dispute highlights a persistent structural ambiguity within the Nigerian entertainment industry regarding personal artist revenue streams and corporate managerial representation. Recording artists frequently operate under loose, family-oriented management structures during their early years, postponing formal incorporation. When commercial valuations surge into millions of dollars, the lack of definitive written employment contracts creates fertile ground for legal disputes.
Peter Okoye’s assertion of no direct employment contract clashes directly with Jude Okoye’s long-standing role as operational director, executive producer, and strategic manager. In standard corporate practice, a manager secures a percentage commission across all revenue streams, including performance royalties, publishing agreements, and brand endorsements. The absence of a clear, executed management agreement leaves the courts to interpret whether informal family arrangements constitute legally binding employment relationships.
SACEM Performance Rights and Author-Publisher Rules
International collection societies like France’s SACEM operate under strict author-publisher frameworks. Performance royalties collected globally are divided between the writers of the musical compositions and the registered publishers. When artists register their works independently without assigning publishing rights to an exclusive management entity, royalty payments flow straight to the individual creators.
This operational mechanic protects primary songwriters from unauthorized third-party deductions, but it also creates tension when a manager acts as both executive director of a corporate label and administrative facilitator for foreign registrations. Navigating these multi-jurisdictional royalty flows requires meticulous separation of publishing assets from corporate operational revenues.
The Employment Contract and Corporate Entity Debate
P-Square’s historical business operations involved multiple corporate entities, notably Northside Entertainment and Northside Music Limited. Corporate governance records show that overlapping management duties often blurred the lines between personal artist accounts and corporate treasury holdings. Plaintiffs and defendants frequently interpret these corporate structures differently when calculating fiduciary responsibilities.
| Entity / Asset | Primary Function | Disputed Financial Scope |
|---|---|---|
| SACEM Royalties | International performance rights collection (France) | Over $800,000 collected (2016–2022) |
| Northside Music Limited | Corporate management and catalog administration | N1.3 billion and $1 million EFCC fraud charges |
| P-Square Master Catalog | Recorded musical works and publishing assets | Triggered 2022 catalog sale audit |
The 2022 Catalog Sale Audit and EFCC Charges
The chain of events leading to the Federal High Court began during high-stakes negotiations in 2022 to sell the multi-million dollar P-Square master catalog. Prospective buyers demanded comprehensive financial audits and clear chain-of-title verifications. These internal due diligence requirements exposed discrepancies in backend royalty records and sparked intense disputes among the brothers.
As audit demands escalated, formal requests for accounting led to counter-accusations regarding historical revenue management. The inability to reconcile internal accounts amicably prompted external petitions to anti-graft agencies, ultimately transforming a family commercial disagreement into a high-profile criminal fraud prosecution.
Discrepancies in Backend Royalty Records and Requests
During the proceedings, defense lawyers presented documentation proving that Jude Okoye delivered complete backend royalty statements within six days specifically between October 16 and October 22, 2022 following a formal request. This rapid turnaround challenged the prosecution’s narrative of financial opacity.
Under cross-examination, Peter Okoye faced direct questions regarding earlier verbal audit requests. When pressed for documentary proof of demands made prior to October 2022, the witness stated, “No. I don’t have any and I can’t recall.” This admission weakened claims of prolonged financial obstruction by the defense team.
Evolution of Northside Music Limited Financial Operations
Financial movements managed under Northside Music Limited formed the core of the EFCC’s seven-count indictment. Investigators analyzed banking transactions, foreign wire transfers, and operational disbursements spanning several years of peak music production. Defense representatives countered these claims by presenting operational financial ledgers showing that corporate funds were deployed directly toward music video production, promotion, and group overhead costs.
Broader Legal Impact on Nigerian Entertainment Sector
The high-stakes litigation between the Okoye brothers establishes critical legal precedents for the rapidly expanding Afrostars and Afrobeats music industry. As Nigerian music catalogs achieve multi-million-dollar valuations on global markets, corporate governance, formal split sheets, and transparent royalty distributions become non-negotiable for long-term group survival.
Entertainment lawyers across the region are closely monitoring the trial. The outcome will likely influence how upcoming talent contracts are drafted, emphasizing the importance of separating family ties from corporate governance and defining exact managerial percentages in written, enforceable agreements.
Standardizing Music Catalog Ownership and Management Contracts
Industry stakeholders must implement rigorous legal frameworks to protect group assets. Essential steps include executing formal split sheets immediately upon song creation, establishing clear publishing agreements with independent collection societies, and separating management commissions from artist performance earnings.
, regular third-party financial audits prevent misunderstandings from escalating into criminal investigations. Establishing transparent corporate ledgers ensures that all stakeholders have real-time visibility into backend royalties and foreign distribution accounts.
Next Steps for the Federal High Court Trial in December 2026
Legal analysts anticipate intense arguments when the Federal High Court reconvenes. The December 8 and 9, 2026 hearings will feature continued cross-examination of key witnesses and the introduction of additional corporate financial records by the defense team.
The final ruling by Justice Alexander Owoeye will carry profound implications for both parties. Beyond the immediate criminal liabilities tied to the N1.3 billion and $1 million charges, the verdict will formally redefine how Nigerian courts view the legal boundaries between creative performance rights and managerial remuneration.
Frequently Asked Questions
What is the core dispute in the Peter Okoye and Jude Okoye court case?
The dispute centers on allegations of financial fraud brought by the EFCC over N1.3 billion and $1 million, alongside Peter Okoye’s admission in court that he collected over $800,000 in SACEM royalties without sharing funds with his manager and brother, Jude Okoye.
What are SACEM royalties, and why did Peter keep them?
SACEM is a French professional royalty collection society that distributes performance rights earnings to authors, composers, and performing artists. Peter Okoye testified that these funds were strictly for artists and creators, maintaining that Jude Okoye was not a member of P-Square and had no direct claim to the money.
What are the charges brought by the EFCC?
The Economic and Financial Crimes Commission filed a seven-count criminal charge against Jude Okoye and his company, Northside Music Limited, alleging financial diversion and fraud amounting to N1.3 billion and $1 million.
When does the trial resume?
Justice Alexander Owoeye adjourned the Federal High Court trial to December 8 and 9, 2026, for the continuation of cross-examination and presentation of defense evidence.